

Go Program Way2Go Card analysis by Appwee
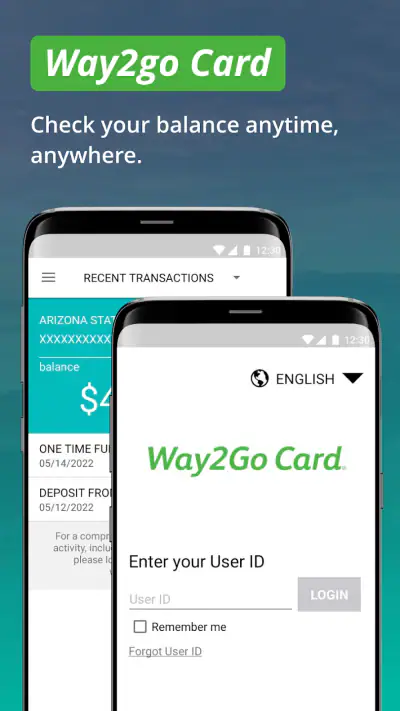
I use Go Program Way2Go Card as a focused way to keep an eye on a Way2Go Card account rather than as a general banking app. That distinction matters. Its job is narrow but useful: it brings your available balance and transaction activity into one place, so you can check whether a payment has arrived, review recent spending, and avoid relying on memory when managing card funds.
The app is free, aimed at everyone, and developed by Conduent Incorporated. It belongs in the finance category, but it does not try to replace a full everyday bank account. In my experience, that limited purpose is both its main strength and its biggest boundary. If you already use a Way2Go Card and want a quick account companion, it can be practical. If you are looking for budgeting tools, bill payment, savings goals, or a broad view of several financial accounts, you will probably need something else alongside it.
How the everyday Way2Go Card routine works
The most useful habit is simple: open the app before making a decision that depends on your card balance. I would check it before buying groceries, paying for fuel, or making a larger purchase, especially when another deposit or recent transaction may have changed the amount available. That small pause is more dependable than estimating from an old receipt or trying to remember the last time the card was used.
The balance view is the natural starting point. I treat it as a snapshot of what I can reasonably use, not as a substitute for planning. After checking the amount, I move to transaction activity and look for the latest purchases or credits. This two-step routine is more valuable than repeatedly staring at the balance, because the activity list gives context when the number looks different from what I expected.
A realistic example is a busy weekday when I use the card for a morning purchase and later need to know whether I have enough available for an evening expense. Instead of searching through paper records, I can open the app, inspect the current balance, and scan the recent activity. If the result still looks unclear, I would avoid treating an unrecognized or unexpected entry as something to ignore. The app helps me notice the issue; it does not remove the need to follow up through the appropriate Way2Go support channel.
That is the first important trade-off. The application makes monitoring easier, but monitoring is not the same as managing every part of a financial life. It is best viewed as a dedicated window into the card account. I would not install it expecting a complete personal-finance dashboard or a replacement for a bank’s broader mobile service.
The audience is also quite specific. It makes sense for someone who actively receives or spends funds through a Way2Go Card and wants access to account information from a phone. It is less relevant for a person who does not have that card, or for someone whose main goal is to combine checking, credit, investment, and cash accounts in one place. Choosing it because it is free would be a mistake if the underlying card is not part of your routine.
What I check first after opening it
I start with the available balance, then review the newest transaction entries rather than scrolling aimlessly through older activity. This order prevents a common error: seeing a familiar balance and assuming everything is current. A recent transaction can explain a change, while an expected deposit or adjustment may need a closer look if the amount does not line up with my records.
I also use the app as a confirmation tool after important card activity. For example, after using the card at a shop, I can return later and check whether the transaction appears as expected. That does not mean every entry will necessarily match my mental note immediately, so I avoid making a second purchase solely because I have not yet seen the first one reflected. The sensible workflow is to check, wait when appropriate, and keep the receipt or other record for anything important.
One practical tip is to make the review part of an existing routine instead of opening the app only during a crisis. Checking before a weekly shopping trip or after a known payment creates a clearer picture of how the card is being used. The benefit is not a sophisticated budget calculation; it is fewer surprises caused by forgotten transactions and outdated assumptions.
Settings and phone habits worth checking
The app itself is intentionally straightforward, so the most useful “settings” are often the habits around it. I would first make sure the phone is running a supported operating system. The minimum requirement is OS 10, which is worth checking before troubleshooting an installation or update problem. A compatible phone does not guarantee a perfect experience, but an older unsupported system can create avoidable friction.
I would also keep the app updated when a newer version is offered. The current version is 3.3.5, and staying current is a sensible way to avoid problems caused by an outdated installation. I would not expect an update to transform the app into a full budgeting platform; the value of updating here is mainly maintaining a reliable way to view the information the app is designed to show.
Phone-level privacy and security deserve attention because this is a finance app. I use a screen lock on the device and avoid leaving the account view open where another person can casually read it. I also avoid entering card or account information while connected to an untrusted public network. These are not glamorous tips, but they matter more than cosmetic customization when an app displays financial activity.
Another useful habit is to distinguish app access from account security. A phone may remember a login or keep a session available, but that convenience should be balanced against who can access the device. On a shared or borrowed phone, I would be much more cautious. If the device changes hands, I would review the app’s sign-in state and remove access in the appropriate way rather than assuming uninstalling later is enough.
Notifications, if available through the phone and app setup, should be treated as a convenience rather than a complete transaction-monitoring system. I would still open the app and review activity directly when the balance matters. A notification can be missed, delayed, or overlooked; a deliberate check gives me a better chance of spotting something that needs attention.
Small preparation steps that save time
Before relying on the app during a purchase, I would install it and complete the sign-in process at home, while I have time to resolve any access issue. That avoids discovering a password problem at a checkout counter. I would also learn where the balance and transaction activity appear so that a quick review remains quick when I am away from home.
Keeping a basic record of expected deposits and major purchases is another useful companion habit. The app shows account activity, but my own note provides a comparison point. If I expect a payment and the balance does not reflect it, I have a clearer question to investigate. If I see a transaction I do not recognize, I can compare it with receipts and dates before contacting support.
This is where the app feels more useful for experienced users than for someone who opens it randomly. The application does not need elaborate tools to become part of a repeatable system. A fixed checking routine, a secure phone, and a simple personal record can turn a basic balance viewer into a dependable daily checkpoint.
Faster patterns for regular card use
For speed, I prefer a three-part pattern: check the balance, scan the newest entries, and close the app once I know what I need. That keeps the app in its proper role and avoids wasting time searching through information that does not affect the immediate decision. When I am planning a purchase, I focus on available funds and recent activity rather than trying to reconstruct a complete financial history.
A second pattern is to check at decision points instead of after every minor action. Opening the app before a planned shopping trip is more useful than repeatedly refreshing it after each small purchase. Afterward, I can review the activity once I am finished. This reduces unnecessary checking while still giving me a reasonable way to catch an unexpected change.
For people who manage money for a household, the app can also support a simple communication routine. One person can check the current card information, compare it with the agreed spending plan, and share the relevant result verbally. I would not share login details casually, though. Convenience should not lead to several people using the same credentials without understanding the security consequences.
Another non-obvious use is separating “available now” from “safe to spend.” The app helps with the first question, but the second may require remembering upcoming expenses. If I have a known payment later in the week, I do not treat the entire displayed balance as discretionary money. I use the balance as the starting point and reserve what I already know I will need.
That distinction prevents one of the easiest mistakes with any balance app: confusing visibility with budgeting. Seeing the number more clearly does not automatically make the spending decision wiser. The application is strongest when paired with a small personal rule, such as keeping a buffer or recording planned purchases before using the card.
When transaction activity needs a closer look
If an entry looks unfamiliar, I would first compare it with receipts, recent travel, household purchases, and any authorized use of the card. Merchant names can be less obvious than the shop name a person remembers, so context matters. I would not dismiss a transaction simply because the description looks unfamiliar, but I also would not assume fraud without checking the surrounding facts.
If the entry still cannot be explained, the app is the place where I notice the problem, not necessarily the place where every dispute is resolved. I would use the official support process associated with the Way2Go Card and keep the relevant transaction details available. Acting promptly is more sensible than repeatedly refreshing the screen and hoping the issue disappears.
The same approach applies when the balance seems wrong. I compare the displayed amount with recent activity and my own notes, then check whether I may have forgotten a purchase or expected a credit too soon. This workflow is more efficient than contacting support without any details, because I can describe what I saw and what I expected.
Where the app reaches its limits
The narrow focus becomes noticeable if you want more than account monitoring. I would not choose this app as my main budgeting tool because the described purpose centers on balance and transaction activity, not category-based spending analysis, long-term goals, or account aggregation. A dedicated budgeting application or a full-service bank app may be a better fit for those tasks.
It is also not the right choice for someone who prefers to manage money entirely from a desktop or through statements. The appeal is the convenience of checking from a mobile device. If you rarely carry the Way2Go Card or already have another reliable way to see its activity, installing another finance app may add little value.
There is also a difference between a clean interface and a complete explanation of an account. A transaction list can show what happened, but it may not answer every question about timing, adjustments, or a disputed entry. I appreciate the app for giving me a current place to look, while accepting that unusual account situations may require direct assistance.
The app’s public reception is mixed rather than flawless, with an average rating of 3.5 from around 58 thousand ratings and roughly 24 thousand written reviews. I read that as a reason to keep expectations practical. It has a substantial user base, with over a million installs, but popularity does not guarantee that every phone, login situation, or account workflow will feel equally smooth.
That scale does make the app feel like an established companion for its intended card users, yet it does not change my recommendation for people outside that group. The relevant question is not whether many people have installed it; it is whether you need a mobile view of a Way2Go Card account often enough for that access to justify another app on your phone.
How it compares with usual alternatives
Compared with a general banking app, this application is more specialized. A bank app usually offers a broader set of services around accounts, transfers, cards, and financial management. That breadth is useful when a person’s money is spread across several products. The Way2Go companion is more focused, which can be an advantage when I only want to check the card without navigating unrelated banking features.
Compared with a budgeting app, it provides a different kind of value. Budgeting software helps me plan categories, monitor targets, or combine information from multiple sources. This app is better for checking the immediate state of the Way2Go Card and reviewing its activity. I would use a budgeting tool beside it if I needed a broader spending plan, not expect this app to perform both jobs.
Compared with relying on paper records or memory, the mobile view is clearly more convenient for quick checks. Still, paper receipts and personal notes remain useful when I need to investigate a discrepancy. The best setup is not “app instead of records”; it is the app for current visibility and a lightweight record for context.
That comparison leads to a clear decision. Choose it when the card is central to your spending and you value immediate mobile access. Skip it when you need account aggregation, detailed planning, or financial tools beyond the Way2Go Card. In those situations, a broader banking or budgeting option will serve you better, even if you keep another method for checking card activity.
My verdict after building a repeatable routine
I see Go Program Way2Go Card as a practical, purpose-built finance app rather than an ambitious all-in-one money manager. Its strongest feature is the directness of the workflow: open it, check the available balance, review transaction activity, and make a more informed decision. For the right user, that can remove a surprising amount of uncertainty from ordinary purchases.
My recommendation is strongest for people who use a Way2Go Card regularly and want a convenient mobile checkpoint. I would install it before I needed it, confirm that my phone meets the OS 10 minimum, secure the device, and establish a habit of checking before planned spending. I would also keep receipts or a simple note for larger purchases so that unusual activity is easier to understand.
I would be more cautious about recommending it to someone seeking a complete personal-finance system. The app does not replace a budget, a bank relationship, or a support process for complicated account questions. Its limited scope is not a flaw when judged against its purpose, but it becomes a limitation when someone expects broader tools.
As a free app with an Everyone age rating, it is easy to try for eligible Way2Go Card users. The developer is Conduent Incorporated, and the current release is version 3.3.5. Those details matter less than the practical fit: if you need balance and transaction visibility from your phone, it earns a place in a simple money routine; if you need planning and analysis, pair it with something more capable.
My final view is straightforward: use it as a reliable checking point, not as your entire financial strategy. When combined with secure phone habits, regular review times, and a small record of expected spending, it does its focused job well. That honest boundary is also what makes the decision easy. Way2Go Card users who want quick account awareness should find it useful, while people searching for a full banking or budgeting replacement should look beyond it.
Gallery
Go Program Way2Go Card Pros and Cons
- Quickly check your Way2Go Card balance and recent transactions.
- Mobile access makes benefit funds easier to monitor while traveling.
- Transaction alerts can help identify unexpected card activity promptly.
- Useful card-management tools may reduce the need to contact support.
- Official app access can be more convenient than using a mobile browser.
- Features and availability may vary by state or card program.
- Occasional login or loading issues can make urgent access frustrating.
- The app may require frequent updates for reliable performance.
- Not all card disputes or account changes can be completed in-app.
- Users still depend on customer support for complex payment problems.
Go Program Way2Go Card Frequently Asked Questions
What is the Go Program Way2Go Card app used for?
The Go Program Way2Go Card app is designed for people who receive government benefits through a Way2Go Card. After signing in, cardholders can typically review their available balance, check recent transactions, view deposit information, locate participating ATMs, and manage certain card settings. The exact services can vary depending on the state or program that issued your card, so the app should be used together with the official instructions provided by your benefits agency.
How do I register or sign in to the Go Program Way2Go Card app?
To use the app, you generally need an active Way2Go Card and the account information associated with it. Registration may require your card number, personal identification details, and security questions or verification steps. Existing users can sign in with their username and password, while forgotten credentials can usually be recovered through the app or official website. Make sure you download the legitimate application and never share your login details with anyone.
Can I use the app to check my balance and transaction history?
Yes, one of the main purposes of the Go Program Way2Go Card app is to provide convenient access to your card account information. Depending on your program, you can usually see your current available balance, recent purchases, withdrawals, deposits, and other account activity. Remember that displayed information may not update instantly, particularly after a transaction or benefit deposit, so allow time for processing before contacting support about a missing update.
Does the Go Program Way2Go Card app help me find ATMs or avoid fees?
The app commonly includes tools for locating ATMs that accept the Way2Go Card, which can be useful when you need cash while traveling or visiting an unfamiliar area. However, ATM availability, withdrawal limits, and fee policies may differ by state, card program, and machine operator. Before confirming a withdrawal, review any fee information shown on the screen and consult your cardholder agreement for surcharge-free options.
What should I do if my Way2Go Card is lost, stolen, declined, or not working?
If your card is lost, stolen, damaged, or unexpectedly declined, use the app’s support or card-management options if they are available for your program. You should also contact the official Way2Go Card customer service number as soon as possible, especially if unauthorized transactions appear on your account. Avoid relying on unofficial websites or social media contacts, and keep your card details, PIN, and verification information private.














